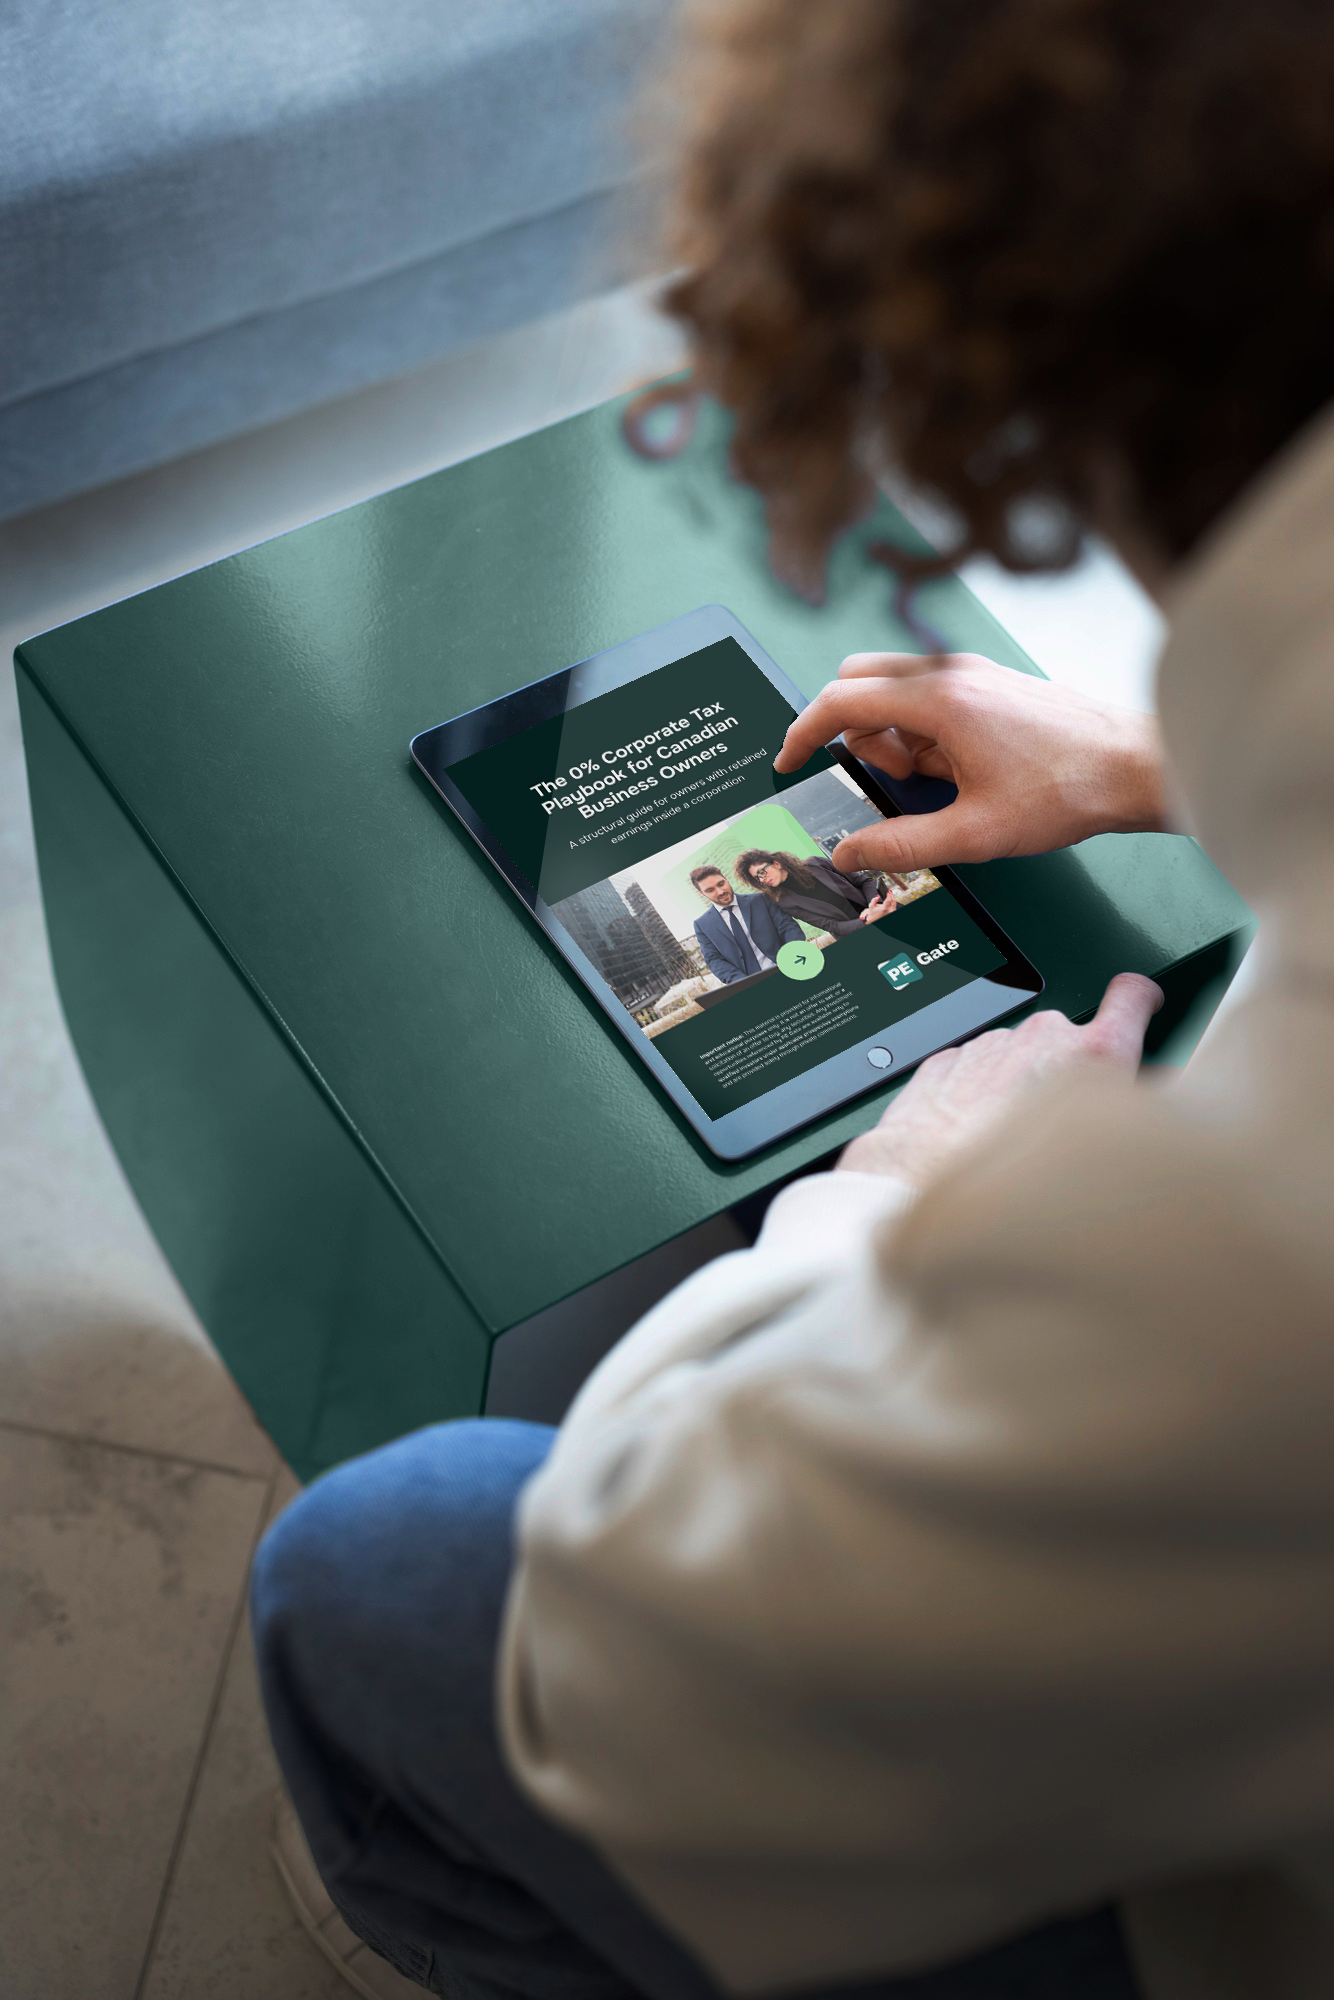
A practical structural guide for owners with retained earnings inside their corporation. Built with insights from PE Gate and Gauvreau Accounting Tax Law Advisory.
For years, the default advice was simple: keep surplus capital inside your company and invest conservatively.That no longer works.Since the tax rule changes on passive income, many incorporated owners unknowingly face:
High upfront corporate tax on investment income
Reduced small business deduction access
Unnecessary complexity and even risk to their LCGE
Passive investing inside an OpCo can trigger significant upfront corporate tax, while excess cash may quietly jeopardize QSBC status ahead of a sale. That’s why sophisticated owners often use holding companies to separate operating risk from capital management.
When structured correctly, connected corporation rules can materially improve dividend tax treatment compared to passive portfolios. Get the structure right, and private operating business investments can compound more efficiently, with fewer tax leaks and fewer surprises at exit.
This guide combines PE Gate’s experience structuring investments in active Canadian operating businesses with Gauvreau Accounting Tax Law Advisory’s technical tax expertise, giving you both strategic and practical perspectives rather than generic tax commentary.

Lorem ipsum dolor sit amet consectetur adipiscing elit ullamcorper mi sem porttitor vel ut quis egestas mauris sapien ipsum diam odio curabitur purus dolor sit amet consectur .
PE Gate is a registered Exempt Market Dealer operating under Canadian securities regulations. All investments are suitable for accredited investors only and carry inherent risks. Past performance does not guarantee future results. All investment decisions should be made in consultation with qualified financial advisors.
View our Client Relationship Disclosure